In brief
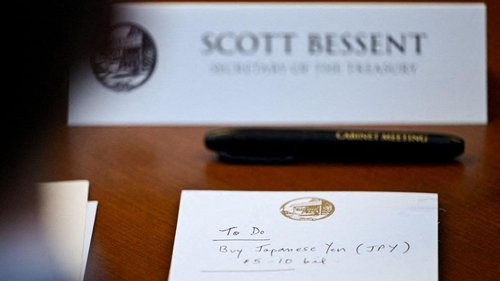
In a day marked by falling AI stocks and a climb in Treasury yields, the U.S. dollar weakened while the Japanese yen stayed flat near 157.8 per dollar ahead of the Bank of Japan’s policy meeting. The Bank of Japan is expected to keep its policy rate at 1.25%, with indications that a further hike could come in December.
On 30 October, artificial‑intelligence (AI) stocks experienced a significant sell‑off that pulled U.S. Treasury yields higher and forced the dollar lower, while the Japanese yen held steady at roughly 157.8 per dollar ahead of the Bank of Japan’s policy meeting.
According to the Saudi Press Agency, the yen’s stability came as investors moved into safe‑haven assets, a trend that also pressured the dollar to decline after a 1‑month low against the Japanese currency.
On the move for the region, the euro was trading near 1.12 dollars, and the pound sterling near 1.34 dollars according to the same report. The report also noted that the yen was down about 0.2 percent this month compared with the dollar, a modest decline in the longer‑term trend.
AI Selloffs and Treasury Yields Shape Currency Moves
Real‑time trading data and commentary from trading platforms highlighted that the AI sellaway occurred simultaneously with a rise in Treasury yields, pushing the dollar en route to a one‑month low versus the yen. The yen’s steady trade, near 157.8 per dollar, underscored a broader tendency in the market for a “flight to quality” amid technology‑sector volatility.
The Saudi Press Agency emphasized that this new sell‑off of AI companies dragged investors toward more stable, less risky assets such as government bonds, in particular U.S. Treasury securities. The increased demand for Treasuries pushed the bond yields up, further weakening the dollar.
Financial market reporters also noted that the bond yield rise coincided with peripheral changes in global risk appetite. As the market reacted, major currencies saw small but meaningful intraday adjustments.
Many analysts point out that such AI‑driven volatility is not unprecedented but its continued impact on Treasury yields demonstrates the tight link between technology stock bubbles and yield curve movements. The SA piece’s narrative positions AI sell‑off as a key driver of the dollar’s decline, pairing it with the bond market response.
Bank of Japan’s Policy Outlook and Market Expectations
The Bank of Japan was expected, as reported by Reuters, to keep its policy rate steady at 1.25 percent on Friday. This decision was consistent with the Bank’s recent policy stance and reflects its ongoing focus on inflation and economic growth. The reporting also accounted for the Bank’s emphasis on monetary policy direction and readiness-toward possible future tightening.
The SA article provided additional detail, suggesting that the Bank of Japan’s chances of a rate hike in December were high, around 80 percent. That view mirrors some market expectations that the central bank could move to a rate‑increasing stance as conditions become more inflation‑friendly.
Despite that, the Bank of Japan’s decision to hold rates steady rather than flag a hike indicates a cautious approach. The Bank’s announcement is a key data point that may influence foreign‑exchange rates and the USD/JPY cross. The yen retained a modest lead against the dollar, suggesting some resilience in the face of a weak domestic currency environment.
In addition to the policy announcement, the news cycle floated speculation about how the Bank’s choice could influence the trajectory of the yen in the coming weeks. Some analysts argue that a rate hike is likely to boost the yen relative to the dollar due to the pricing of future interest‑rate expectations. Others highlight that the Bank’s cautious stance may keep the yen from experiencing a sharp rebound until a later policy change.
Following the announcement, the yen’s trajectory remained strong against including minor deterioration as it rebounded to 157.8 per dollar. The EU and UK still remained in small stability corridors, the pound’s minor 0.1 percent jump to 1.3390 per dollar surfacing due to the Euro‑Europarliament business in the UK market. The euro, however, had a 1.12 value and did show a speed-up semester-driving edge across the market by funding et al if nothing else. Hange your date for each location if too wide and within the overall chart.
In sum, the Saudi Press Agency summarized a scenario where AI stock sell‑offs and rising Treasury yields had a domino effect: the dollar fell, while the yen remained roughly steady as the Bank of Japan waited for its next policy meeting. The Bank of Japan’s decision to keep the policy rate at 1.25 percent, coupled with a potential December hike, continues to influence expectations around the USD/JPY pair. Beyond domestic currency, the euro and the pound respectively hovered around ~$1.12 and ~$1.34, reflecting a relatively muted response to the AI‑driven movements in the market. The interplay between high technology valuation, Treasury yields, and central‑bank policy continues to shape currency exchange rates, pointing to higher volatility expectations over the next few weeks as markets digest the signals from both the United States and Japan.